Jessica Ellerm
Business Development Manager at Tyro Payments
Sydney, Australia
@JessicaEllerm | LinkedIn Profile
As a Business/Partner Development Manager, my role is to facilitate new Tyro partnerships. Traditionally we have focused on building a partner community with local and global point of sale software vendors, however as we are evolving as a banking business we’ll be seeking new partnerships in other software verticals, like the cloud accounting sector. In addition to this, I work with our sector specific Business Development Managers to help them nurture their existing partnerships more effectively and build out joint marketing strategies. We’re a very non-hierarchical, flat organisation, where roles and responsibilities are fluid, according to a project’s requirements, which as you can imagine, is quite revolutionary for a bank!
You are an active blogger (jessicaellerm.com/). What is it about the writing process that you enjoy? Do you believe this approach extends both Tyro’s brand along with your own?
I’m an eternally curious person, so am constantly on the look out for great ideas and fascinating stories that firstly I can educate myself on, then share with others. I’m also interested in creating and linking new ideas, thinking about things in fresh ways. Blogging gives me the opportunity to do all of this and more, then connect with other likeminded fintech people within the fintech community around the world. I think the global nature of blogging has been the most exciting aspect to date – suddenly you’re having conversations with people in the UK, US and Switzerland – it’s an eye-opener. Tyro’s are curious people by nature as well. It is certainly a business that attracts an entrepreneurial minded person, someone looking to challenge the status quo. You have to be brave (and somewhat naive!) to take on the banks in Australia. I believe that entrepreneurial attitude of rolling up your sleeves and jumping in is absolutely a quality of the Tyro organisation, and our customers.
How would you describe the Australian FinTech scene?
Growing rapidly by the week! Currently it is dominated by peer to peer lenders, both to the personal and business lending market, however the personal financial management sector is growing, along with the roboadvisor industry. We’re still a way behind the UK and the US, but that will change in time. The barriers to entry here are relatively high and there are less investor incentives in the form of tax breaks like their are in the UK, which doesn’t help. But the opportunities are immense. Despite Australian banks achieving record profits year after year, many are failing to invest in innovation for their customers. That’s where smart fintech comes in.
Do you believe consumers in Australia are more inclined to adopt FinTech solutions than consumers in Europe or the U.S.?
I’m probably a bit more cynical on this one and would say no, they’re not. A lot of this has to do with a lack of awareness of bank alternatives. I see this as a key obstacle to Australian fintech companies achieving similar market success to companies like Lending Club. The banks in Australia have huge brand power, deep pockets and incredible mindshare. It doesn’t help that they came out relatively unscathed after the GFC, meaning customers have really had little reason to look elsewhere. This will undoubtedly change over the next year or so as the groundswell of fintech startups starts to be felt. Companies like SocietyOne, an Australian peer to peer lender are executing on some great marketing initiatives, like providing consumers with a free credit score. It’s a great way to ease potential customers into their world and I look forward to seeing similar innovative marketing tactics like that from fintech startups.
You are a frequent contributor to Brett King’s “Breaking Banks” podcast. How did you meet Brett and what prompted you to take a correspondent role with his show?
I was (and still am) a regular listener to the show and realised that while we had some great stories to tell in Australia, they weren’t getting heard. So, I flicked Brett and email with some ideas of potential contributors that I knew from my network of contacts in the space. Both Brett and the production team thought it would bring a great new dimension to the show and it snowballed from there.
Who(m) do you believe has had the most influencing with respect to influencing your own career?
Probably the single most influential person in my career to date has been Jost Stollmann, the CEO of Tyro. He has an incredibly strong vision for the company and has steered it through some very tough market conditions. Like any start-up, Tyro has a lot of passionate people with strong opinions – it’s not easy keep everyone in alignment, but somehow he does it. I spend a lot of time observing and learning from him.
Who do you consider to be strong women leaders in the banking / FinTech space?
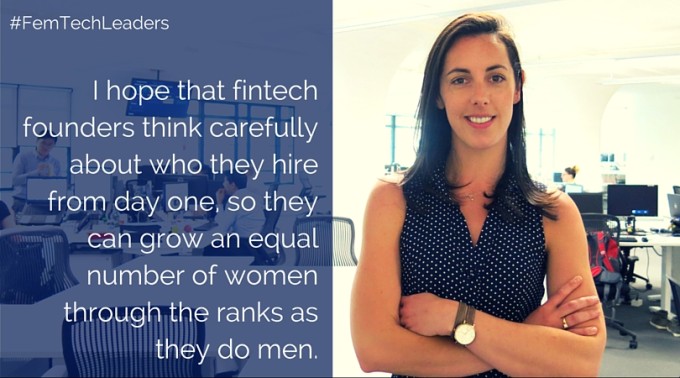
Gail Kelly, the former CEO of Westpac did an immense amount to push the female agenda during her tenure and this really set the tone for a number of other banks. Diversity at senior management level and board level is still lacking in Australia, and not just in the banking and fintech space. I hope that fintech founders think carefully about who they hire from day one, so they can grow an equal number of women through the ranks as they do men. Ultimately diversity of thought within a business leads to better business decisions. Hiring can’t be a passive decision purely based on skills. It needs to take into account culture as well.
What do you see as the 3 leading future trends for FinTech?
The three big trends I see are personalisation of financial services through personal financial management tools and applications, roboadvisors replacing traditional (and expensive) financial advisors and thirdly a big drive to go mobile with any product you build. Our product team are absolutely looking through all product concepts these days with a mobile lens. For Tyro it’s about how can we help time poor businesses manage all financial aspects of their business from the palm of their hand.
How much of an issue is gender diversity with respect to FinTech companies in Australia? Do you believe there are any key differences than other global regions?
I actually think a lot of the major banks are doing a pretty good job when it comes to gender diversity, both within their organisations and at a board level. Australian Fintech is not doing so well, going by the make up of the start-ups I see coming through and the composition of the meet-ups I attend. Sometimes you can count on one hand the number of women in a room of +100 people! I’d say the problem is global, but I don’t know enough about the UK and US communities, which are the most mature, to comment. The technology sector in Australia is relatively immature, although we don’t seem to have the same ‘bloke’ culture that you hear about Silicon Valley having. Either way, we need to actively encourage more women to step into start-up roles, be they in fintech or other sectors.
About Tyro:
In 2005 Tyro was the first and only bank in Australia to obtain an acquirer only license. Off the back of this we built Australia’s first cloud based EFTPOS system, fully integrated into a businesses point of sale software, requiring no middleware or complex integration software. This significantly widened the market for integrated EFTPOS, and small businesses were suddenly able to afford what had been to date only available to big business, due to high technology costs from the incumbent banks and middleware providers. Since then we have acquired over 13,500 customer and partnered with over 120 point of sale providers. We are entering a new banking phase now, having just been granted a general banking authority by the Australian Prudential Regulatory Authority that allows us to take money on deposit and to advance money to Australian businesses. This is the first time a challenger has been authorised to compete head-on with the banking establishment in Australia.
Tyro is unique in that it advocates tirelessly for small and medium Australian businesses – no other bank in Australia can claim the same degree of focus on this sector as Tyro can. In doing so, we have elevated the competitive landscape and bought real choice to businesses. Not only that, we were the first to really leverage cloud technology in the payments space in Australia. Now we are building out the banking disruption ecosystem with Australia’s first FintechHub (http://tyrofintechhub.com/).

© 2015 | FemTech Leaders
Start the conversation